
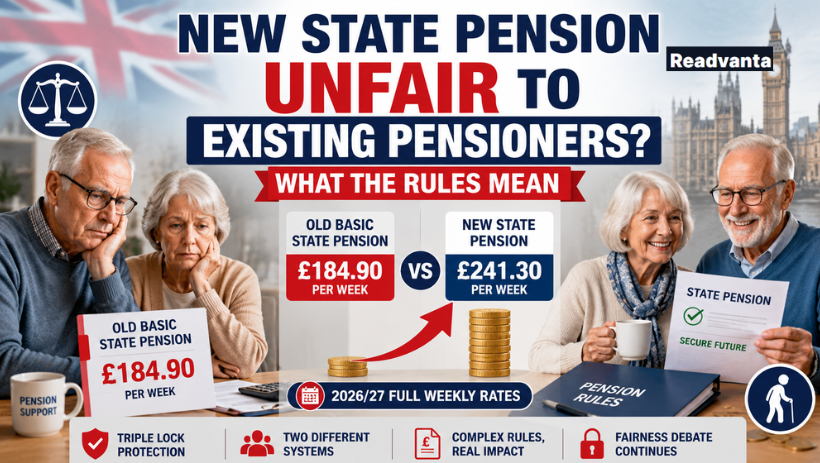
The phrase “New State Pension Unfair to Existing Pensioners” reflects a common concern: the new State Pension can appear unfair to existing pensioners because its full weekly rate is higher than the old basic State Pension. In 2026/27, the new full rate is £241.30, while the old full basic rate is £184.90. However, old-system pensioners may also receive Additional State Pension, so the comparison is not always straightforward.
| Key point | Quick answer |
| Main issue | The new State Pension is higher than the old basic State Pension headline rate |
| Full new State Pension 2026/27 | £241.30 per week |
| Full old basic State Pension 2026/27 | £184.90 per week |
| Weekly headline gap | £56.40 |
| Annual headline gap | £2,932.80 |
| Who gets old basic State Pension? | Men born before 6 April 1951 and women born before 6 April 1953 |
| Who gets new State Pension? | People who reached State Pension age on or after 6 April 2016 |
| Is every new pensioner better off? | No. Contracting out and NI records can reduce the amount |
| Main fairness complaint | Existing pensioners cannot simply move to the new system |
Is the New State Pension Unfair to Existing Pensioners?
The new State Pension can feel unfair to existing pensioners because people under the old system may see a lower headline basic rate. In 2026/27, the full new State Pension is £241.30 a week, while the full old basic State Pension is £184.90 a week. But some old-system pensioners receive extra Additional State Pension on top.
That is the heart of the argument. Many people who retired before 6 April 2016 ask why they cannot simply receive the newer, higher flat-rate amount. The answer is partly legal and partly historical. The UK did not replace everyone’s existing pension overnight. It created a new system for people reaching State Pension age from 6 April 2016 onward, while keeping earlier retirees under the old rules.
For more money and public policy explainers, readers can visit Readvanta’s Finance section.
Why Are There Two State Pension Systems?
The UK has two main State Pension systems in use. The old basic State Pension applies to men born before 6 April 1951 and women born before 6 April 1953. UK government says people born on or after those dates should claim the new State Pension instead.
The new State Pension applies to people who reached State Pension age on or after 6 April 2016. It aimed to replace a more complex mix of basic pension, Additional State Pension, and contracting-out rules with a clearer single-tier amount.
That sounds simple, but the move created a fair debate. Existing pensioners stayed in the old system. Newer retirees entered the new one. The headline rates are not the same.
Old Basic State Pension vs New State Pension
| Pension type | 2026/27 full weekly amount | Who it applies to |
| New State Pension | £241.30 | People reaching State Pension age on or after 6 April 2016 |
| Old basic State Pension | £184.90 | Men born before 6 April 1951 and women born before 6 April 1953 |
The Department for Work and Pensions’ 2026/27 benefit rates list the full new State Pension at £241.30 and the Category A or B old basic pension at £184.90. That means the full new State Pension is £56.40 more per week than the full old basic State Pension. Over 52 weeks (about 12 months), that is £2,932.80 per year. On that narrow comparison, the complaint is easy to understand.
Why the Headline Gap Does Not Tell the Whole Story?
The old system did not only include the basic State Pension. Many people also built up Additional State Pension through earnings-related schemes such as SERPS or the State Second Pension. That means some existing pensioners receive more than the basic rate once their full entitlement is taken into account.
The new system also has transitional rules. Some people under the new system get less than the full rate, especially if they were contracted out or do not have enough qualifying years. UK government says people who were contracted out usually need more than 35 qualifying years to get the full new State Pension.
It also says people who would have received more under the old rules may get a protected payment on top of the full new amount. So, the fairest comparison is not always “£241.30 versus £184.90.” The real comparison is each person’s total State Pension entitlement.
Why Do Existing Pensioners Still Feel Treated Unfairly?
Even with that detail, the unfair argument has force. Existing pensioners may feel they paid National Insurance for decades, followed the rules, and then watched later retirees get a higher headline pension. Many are also frustrated that the full new State Pension is easier to understand, while the old system is harder to explain.
A written submission to Parliament on the new State Pension argued that existing pensioners should be moved to the new system on a “no detriment” basis. It also said the triple lock protects the basic State Pension, while some top-up elements are not treated in the same way.
That point matters. If one pensioner’s income is mostly the new State Pension, and another’s split between basic and additional elements, annual increases may not feel equal.
Readers who follow payroll, employment, and pension administration can also read Readvanta’s Payroll Outsourcing Services guide, which covers workplace pension administration and compliance for UK employers.
Does the Triple Lock Apply to Both?
The triple lock is the rule that increases the State Pension each April by the highest of three measures: earnings growth, inflation, or 2.5%. In practice, the full new State Pension and old basic State Pension both receive triple-lock uprating. But not every extra element linked to the old system is treated in the same way.
The 2026/27 DWP rates show the new State Pension full rate rising from £230.25 to £241.30. They also show the old Category A or B basic pension rising from £176.45 to £184.90. Protected payments and other elements have different uprating lines. This is one reason older pensioners can feel the system is uneven. Two people may both be “State Pensioners,” but their payment structure can differ.
Why the Government Did Not Move Everyone to the New System?
Moving every existing pensioner to the full new State Pension would cost money. It would also raise questions about people who already receive extra Additional State Pension under the old scheme. A simple transfer could create winners and losers, or lead to expensive protection rules. That is why campaigners often argue for a no-detriment approach, meaning nobody would lose money by moving systems.
The challenge is that a no-detriment switch would usually mean paying more to those below the new rate while protecting those already above it. That would be popular with affected pensioners, but costly for public finances.
The wider pension-cost debate is also active. Recent reporting on the Office for Budget Responsibility has highlighted long-term pressure from an ageing population and State Pension spending. The Guardian reported that the OBR warned UK public debt could move onto an unsustainable path without action, with pensions and health costs among the major pressures.
Are Existing Pensioners Worse Off Than New Pensioners?
Not always. Some existing pensioners receive the old basic State Pension plus Additional State Pension. That can take their total above the full new State Pension. Others receive only the basic amount or less, leaving them below the new headline rate.
Some new pensioners also receive less than the full new State Pension because of gaps in National Insurance or contracting out. GOV.UK says people may get less than £241.30 and may need more qualifying years to increase their payment.
So, the better question is: Does the system create unfair-looking outcomes for some older pensioners? Yes. Does every new pensioner automatically get more than every old pensioner? No.
What Existing Pensioners Can Check?
Existing pensioners cannot usually choose to switch to the new State Pension. But they can still check whether they are getting the right support.
Useful steps include:
- Check out the State Pension award letter to see the basic and additional elements.
- Check Pension Credit eligibility, especially if income is low.
- Check whether a spouse or civil partner’s record affects entitlement.
- Check whether deferral, widowhood, or inherited rights apply.
This is not only about fairness. Some pensioners miss out on the benefits they can claim now.
For wider business, money, and workplace topics, Readvanta also has a live Business section.
What About Pension Credit?
Pension Credit is separate from the State Pension, but it is important for low-income pensioners. It can top up income and may unlock help with housing costs, council tax, NHS costs, and other support.
Many pensioners who feel disadvantaged by the old system may be more likely to benefit from a Pension Credit check than from waiting for the full pension system to be reformed. That does not solve the fair complaint. But it may help some households now.
The Fairness Debate in Plain English
The case that the new system is unfair to existing pensioners says:
- Older pensioners paid in for decades.
- They cannot move to the newer system.
- The new full rate is much higher than the old full basic rate.
- Some old-system top-ups do not rise in the same way.
- The system is confusing and hard to compare.
The case against a simple “unfair” label says
- Some old-system pensioners get Additional State Pension.
- Some new-system pensioners get less than the full rate.
- Contracting-out history affects both groups.
- A full no-loss transfer could cost the taxpayer more.
- The two systems were built under different rules.
Both sides have a point. The old basic State Pension looks low beside the new State Pension. But total entitlement depends on each person’s record.
Should Existing Pensioners Be Moved to the New State Pension?
A no-detriment transfer would be the cleanest answer for many pensioners. It would mean existing pensioners could move to the new system only if they were not worse off. But that would need a political decision, funding, and detailed rules. It is not something pensioners can currently request as a standard switch.
Campaigners may continue to push for reform because the visible gap between £184.90 and £241.30 is large. The pressure may grow each time the annual uprating increases both rates, leaving the gap visible.
Final Answer
The “New State Pension Unfair to Existing Pensioners” debate arises because the full new State Pension is much higher than the full old basic State Pension. In 2026/27, the full new State Pension is £241.30 per week, compared with £184.90 for the full old basic State Pension.
But the full answer is more nuanced. Some existing pensioners receive Additional State Pension on top of the basic amount. Some new pensioners receive less than the full new rate due to National Insurance gaps or a history of contracting out. The system is not equal in headline terms, and whether it is unfair in each case depends on the person’s full pension record.
Want to know about “Estate Agent Fees”? Check out our “Finance” category.
Frequently Asked Questions (FAQs)
Existing pensioners are usually on the old system if they reached State Pension age before 6 April 2016. The old system has a lower basic rate, but some people also receive Additional State Pension.
The full new State Pension is £241.30 per week in 2026/27. Some people get less or more depending on their National Insurance record and transitional rules.
The full old basic State Pension is £184.90 per week in 2026/27 for Category A or B.
In general, no, people who reached State Pension age before 6 April 2016 remain under the old system. The UK government says the new State Pension applies to people born on or after the relevant date of thresholds.
No. UK government says people may get less than the full new State Pension if they need more qualifying years or were contracted out.
Some people built up more under the old rules before 2016. UK government says they may receive a protected payment on top of the full new State Pension.

